

Angel Investor Return Expectations for MENA Founders
Building in MENA? You don't have to do it alone.
Join 300+ founders in the Founder Connects Residency. Monthly squad calls, warm intros, $3M+ in perks, and much more. All for less than your monthly coffee budget.

Angels backing pre-seed and seed rounds in the UAE and MENA typically look for 10x to 30x on the deals that work, usually from about 7% to 15% combined ownership, because most of their cheques will return little. This guide shows the return maths behind that target, how stake, valuation and instrument change it, and what to prepare before you name a price.
Those expectations are set by cheque size, ownership, instrument choice and holding period, not by how polished the deck looks. Exits in this market are uneven rather than routine, so angels price that risk into every cheque.
If you want angels to back you, treat the return conversation as a design exercise, not a personality test.
What an Angel Investor Actually Underwrites in MENA
A founder walking into a first angel meeting in a DIFC co-working space usually thinks the investor is underwriting the product. They're not. They're underwriting your judgement under pressure, the clarity of the opportunity, and whether the business can travel beyond one city or one customer type.
The first thing an angel buys is optionality
In MENA, an angel cheque is often a bet on whether you can turn local traction into regional relevance. That means the investor is looking at the founder's behaviour when cash is tight, the quality of the story on the slide, and whether the business can later stretch across the UAE, Saudi Arabia, and Egypt without collapsing under complexity. In the UAE, the legal wrapper matters too, because investors notice whether the company can operate cleanly under an ADGM or mainland structure.
Practical rule: if your pitch sounds like a small business asking for working capital, angels will price it like a small business. If it sounds like a scalable company with a large addressable market, they'll start thinking in multiples.
The other thing they're underwriting is their own portfolio logic. One angel rarely writes to win on every cheque. They write a spread of bets, often somewhere between a small handful and a larger set, expecting a few winners to pay for the misses. That's why founders who pitch “steady returns” are talking past the actual buyer.
If you want the blunt version, the angel is not buying a dividend stream. They're buying upside. That difference changes the whole conversation about ownership, structure, and timeline. It also explains why a clean narrative matters more than a crowded metrics slide in the earliest stages.
Timing is the other half of the return. For how long angels expect to wait, see this guide on angel investor exit expectations and 5 to 10 year timelines.
The Return Maths Angels Use to Price a UAE Bet
An angel in the UAE is rarely doing elegant spreadsheet theatre. They're running a simple mental model, how much ownership they get, how long their money will be stuck, and what exit size could turn a risky cheque into a meaningful outcome. The exact numbers shift deal by deal, but the logic doesn't.
What the cheque has to become
A UAE-focused guide says individual angel cheques commonly range from AED 35,000 to AED 185,000 per investor, while pre-seed rounds often sit between AED 500,000 and AED 2,000,000. It also notes that angels often target 7% to 15% aggregate ownership at pre-seed or seed and should plan for a 5 to 10 year time frame before expecting an exit (Founder Connects, angel investors in Dubai guide). Another UAE guide places typical angel cheques at USD 50,000 to USD 250,000, or AED 180,000 to AED 900,000, with angels often seeking around 10% to 25% equity (Dubai South Business Hub funding sources guide).
That range matters because it shows what angels are trying to buy, enough equity for the upside to matter, but not so much that the founder is crippled before the next round. If the cheque is small, the angel needs the deal to multiply hard. If the cheque is larger, they still need the company to clear a serious exit, because their cash is trapped for years.
A clean way to think about it
For a practical UAE pre-seed bet, a founder should expect the angel to think in 10x to 30x outcomes on the successful deal, not on the whole portfolio. The portfolio itself needs enough winners to clear the losses, which is why the investor cares about a repeatable path to a large outcome, not just a decent business.
| Angel Return Maths for a Typical UAE Pre-Seed Bet | |||||
|---|---|---|---|---|---|
| Cheque Size (USD) | Post-Money Valuation (USD) | Stake Acquired | Target Multiple | Required Exit Value (USD) | Implied IRR over 7 Years |
| 250,000 | 4,000,000 | 6.25% | 10x to 30x | 40,000,000 to 120,000,000 (before later dilution) | About 39% to 63% a year, if the exit lands in year 7 |
The maths is simple division. A $250,000 cheque at a $4 million post-money valuation buys 6.25%, so a 10x payout of $2.5 million needs an exit of about $40 million, and 30x needs about $120 million. Every later round dilutes that stake and raises the exit value the angel needs, which is why the price you set now matters so much.
If your valuation makes the angel's upside too thin, they'll quietly wait for a better deal. They don't need to argue. They can just pass.
A common mistake is ignoring the exit maths until diligence. By then, the company has already implied a cap, a discount, and dilution path that may not support the angel's return target. That's when a friendly conversation turns into a hard negotiation.
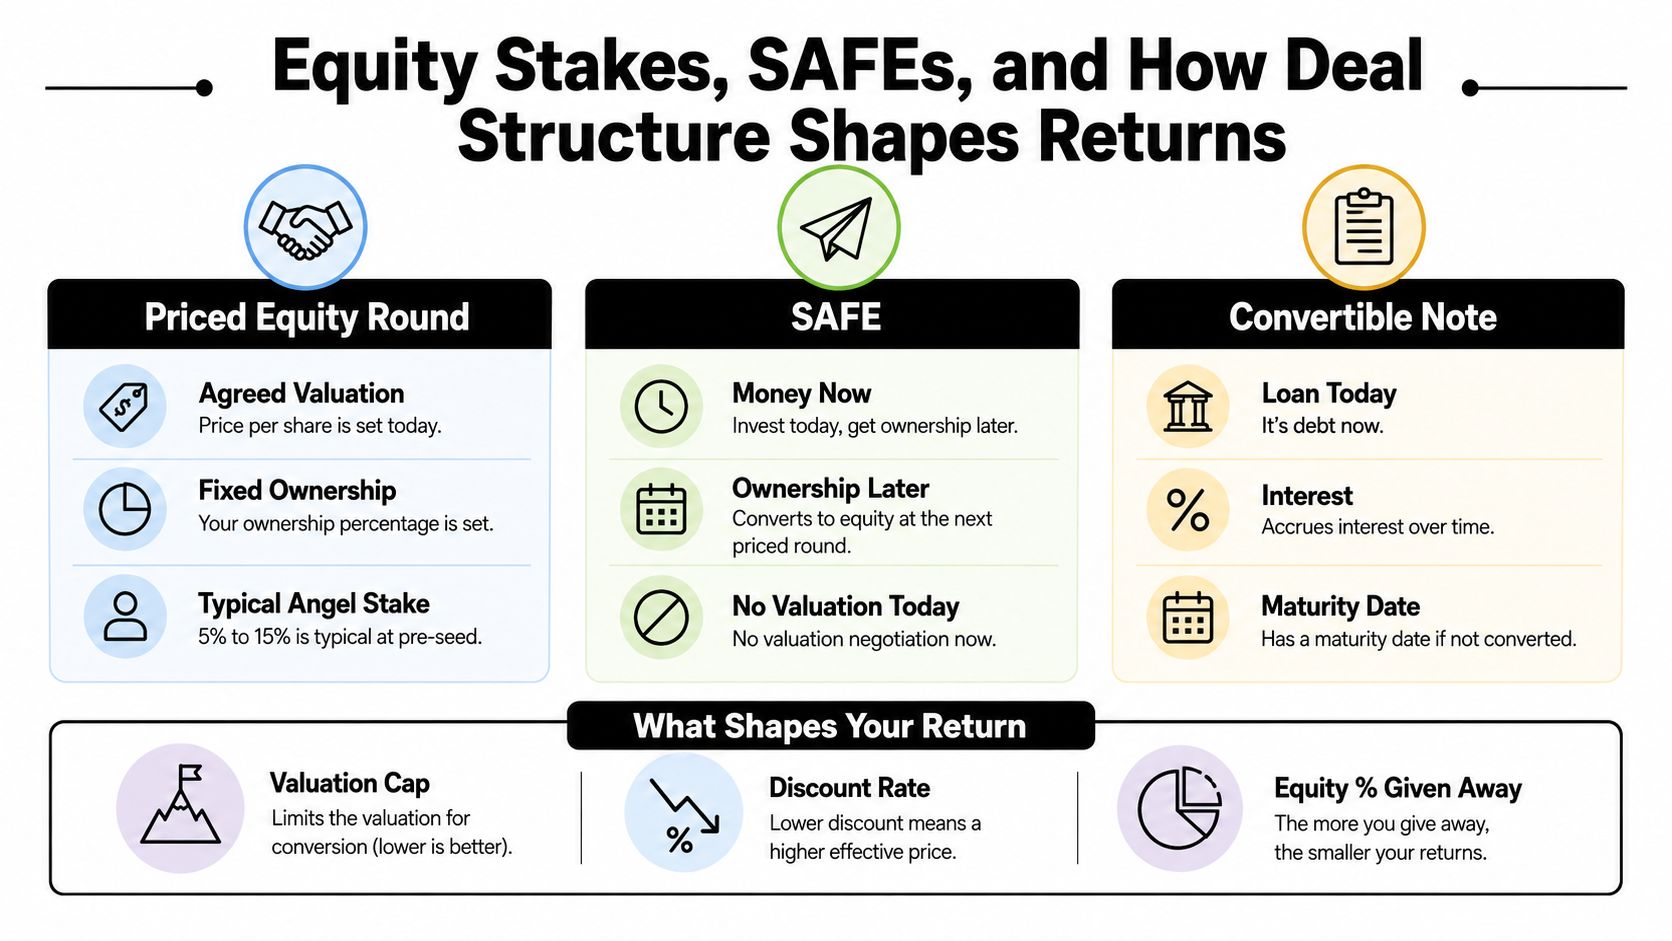
Equity Stakes, SAFEs, and How Deal Structure Shapes Returns
The instrument is not a legal technicality. It's the engine that decides how much of the company the angel actually owns when the upside shows up. If you use the wrong structure casually, you can hand over more equity than you intended without ever “selling” it in the room.
Priced equity and what it actually fixes
A priced round does one useful thing immediately, it fixes valuation today. That gives the angel a known ownership percentage and gives you a clean cap table from day one. In early UAE rounds, that's often easier to reason about than a document stack full of conversion mechanics, especially if the company already has enough traction to justify a clear price.
SAFEs and convertible notes are not the same thing
Angel investors in the UAE commonly use SAFE notes in early-stage rounds, and Hub71 describes its SAFE as a promise to give an investor shares later in exchange for cash now, with conversion at the next priced round and an uncapped, no-discount, future-looking MFN structure in its programme offer (Hub71 FAQ). UAE legal commentary also notes that SAFEs and convertible notes are widely used because they defer valuation until a later financing round, and that SAFEs are typically simpler than convertible notes, usually without interest or a maturity date (Nour Attorneys, venture capital legal framework).
That distinction matters. A SAFE can make the first cheque feel painless, but it doesn't remove dilution. It postpones the valuation fight. A convertible note adds debt-like features that can create different pressure points later. If the founder does not model conversion properly, the “cheap” money can become expensive ownership.
Use the structure as a negotiation tool
The practical move is not to accept whatever template lands in your inbox. It's to choose the structure that matches the angel's return target and your dilution tolerance.
- Priced equity works when both sides want clarity now.
- SAFE works when you want speed and the next round will set a stronger price later.
- Convertible note works when both sides are comfortable with debt-like mechanics, but it needs closer legal review.
For a UAE-specific walkthrough of the mechanics, read convertible notes vs SAFE for UAE startups.
How the Exit Timeline Changes the Return Maths
The longer an angel waits for an exit, the higher the multiple has to be to earn the same annual return, so the timeline is part of the price. MENA exits often take 5 to 10 years; our guides to angel holding periods and exit timelines cover the wait itself, and this section covers how it changes the maths.
Time is part of the return
A MENA VC exit analysis says the first generation of angels investing in 2015 to 2017 still had not exited by early 2024, and that VC funds usually begin considering exit opportunities in year five after investment (AGBI analysis on MENA VC exit route uncertainty). The point for founders is simple. Liquidity is not a line item you can ignore until later. It is part of the deal from day one, which is why the return window discussed earlier matters so much. If your company cannot survive several financing cycles, the angel's target return is irrelevant because there may be no exit at all.
The regional liquidity pool is thin. IPO windows on local exchanges are limited, strategic buyers are selective, and secondary sales are not a common early escape hatch. That leaves one real path for most angel bets. Build enough value for a later buyer or a later-stage investor to care.
Why the timeline affects ownership today
Longer holding periods change dilution planning. Each future round can cut the angel's stake, so the investor needs enough ownership at entry for the eventual exit to matter. If the first cheque is too small relative to the cap table, the angel may back a company that grows but never produces a meaningful return.
That is why founders should treat timeline and dilution as one conversation, not two separate ones. A SAFE, a priced round, or a convertible note may all get money in the door, but each one sets up the next ownership fight differently. If you do not model follow-on rounds, the “cheap” money can become expensive ownership by the time liquidity shows up.
For a practical planning lens on holding periods, use this guide on angel holding period and return expectations as a reference point when you talk through timing with an investor.
| MENA Exit Reality vs Angel Return Maths | MENA Reality | Global Benchmark | Implication for Angel |
|---|---|---|---|
| Holding period | Often long enough to test patience | Faster liquidity is assumed in many investor decks | Ownership has to be meaningful from day one |
| Exit routes | Concentrated and selective | Broader buyer pools in mature markets | Exit planning starts early, not at Series C |
| Secondary sales | Not common early | More common in deeper markets | Angels usually underwrite primary exit only |
The blunt takeaway for a founder is this. Do not pitch an angel on hope. Pitch a company that can still make the return work after dilution, delayed exits, and a narrow buyer pool.
How Sector and Stage Shift Angel Expectations
A SaaS founder and a regulated fintech founder are not playing the same game. Angels know it, and founders who pretend otherwise usually get priced badly or rejected quickly.
Capital-light companies get judged differently
For capital-light businesses like SaaS and marketplaces, angels want to see evidence that the model can move fast, convert efficiently, and expand without every extra customer costing a fortune. In those sectors, the conversation usually centres on usage, retention, monetisation, and whether the team can build toward meaningful commercial traction without oversized burn.
Regulated or deep-tech businesses need more proof
Fintech, health, and deep-tech stories carry a heavier proof burden. Regulatory milestones, pilot quality, and founder credibility matter more because the path to revenue is longer and more fragile. A PropTech founder in Dubai is often judged on a different timetable than a B2B SaaS founder in Cairo because the proof points, customer cycle, and regulatory friction are not the same.
That difference changes the return expectation too. Angels may tolerate a slower ramp if the eventual outcome can be large and defensible, but they'll expect sharper milestone discipline along the way. If the next round depends on institutional capital, the founder needs to show the exact evidence that removes the next investor's biggest objection.
| Sector and Stage Benchmarks for MENA Angels | |||
|---|---|---|---|
| Sector | Pre-Seed Milestone | Seed Milestone | Typical Valuation Cap |
| Capital-light SaaS | Early customer use and clear retention pattern | Repeatable sales motion and stronger commercial proof | Higher when traction is visible |
| Marketplace | Supply and demand activity that repeats | Liquidity and conversion behaviour that holds | Higher when network effects begin to show |
| Fintech | Regulatory progress and pilot access | Compliance readiness and trusted distribution | Often tighter until proof is strong |
| Health or deep-tech | Technical validation and credible commercial pathway | Clinical, regulatory, or deployment milestones | Usually more conservative until risk comes down |
If you're raising in a sector that needs longer proof cycles, do not let the angel judge you on SaaS-style speed. Judge yourself on milestone credibility. That's the cleaner conversation.
Negotiating with Angels Without Giving Away the Company
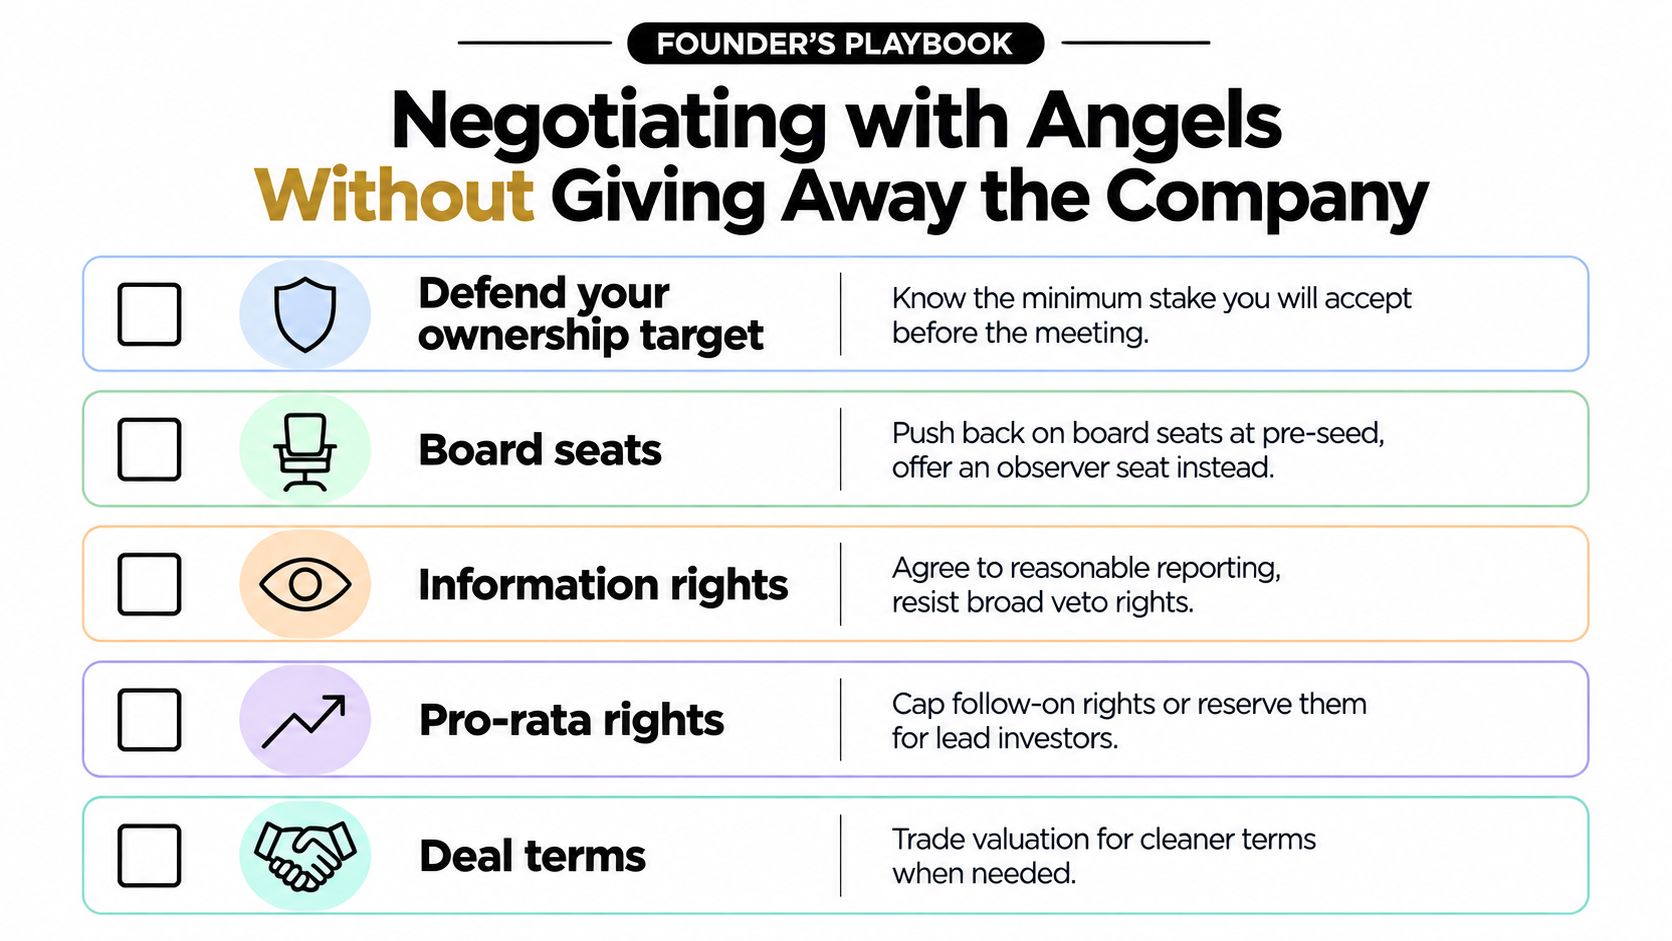
Founders lose money in this meeting by treating it like a polite conversation. It is a capital allocation exercise. You do not need to win every point, but you do need to know which terms cost real equity and which ones are just noise.
Defend the ownership you can live with
Before the meeting, decide the lowest ownership percentage you can accept and still defend in the next round. If you do not set that number, the investor will set it for you. In the UAE, early angel cheques can look harmless on paper, but cumulative dilution after conversion and follow-ons is the core problem.
Use the traction language angels already respect. Talk about cohort retention, contribution margin, signed LOIs, and regulatory clearance. That is more useful than vague confidence. It shows you understand what has to be true before the business can scale.
Push back where the hidden cost sits
Board seats at pre-seed are often too much control for too little capital. Information rights should be reasonable, not invasive. Pro-rata rights are fine for a lead investor who is actively supporting the company, but they should not become a trap that blocks future flexibility.
The terms that cost the most equity are usually the ones founders skim past:
- Valuation caps that are too low for the stage.
- Discounts that stack on top of a weak cap.
- MFN clauses that give later investors an advantage you did not price in.
- Liquidation preferences that shift downside protection too far in the investor's favour.
You do not need to reject every investor-friendly term. You need to know which one buys speed, and which one buys control.
For a useful negotiation reference, read the guide on negotiation tactics for founders raising capital before your next investor meeting.
Aligning Expectations and Your Next Move This Week
An angel meeting goes better when you walk in with aligned maths. Keep the return band clear, the timeline realistic, and the dilution you can live with before anyone opens the deck.
What to lock before the room
Start with your exit story and stress it against UAE reality, not slide-deck ambition. Then match the instrument to the ask, because a SAFE, a convertible note, and priced equity each signal a different mix of control and conversion. Set your position on cap, discount, and pro-rata before the documents get marked up.
A clean weekly plan looks like this:
- Update the cap table: model the dilution from this round and the next one.
- Write one page on exit maths: show what exit range makes an angel cheque rational.
- Prepare three direct questions: ask how the investor handles holding periods, follow-on rights, and conversion terms.
- Book two UAE angel coffee chats: use them to test your assumptions, not just to pitch.
- Send the formal ask within 14 days: momentum matters more than another month of polishing.
Simple script: “We're raising to hit this milestone, at this structure, and we think the credible return case for an angel sits in this range if we execute well.”
That line works because it is blunt. It does not oversell, and it does not apologise for ambition. It gives the investor enough to decide whether the cheque fits their return target.
Angel investing in MENA is a deal-design problem with a timeline attached. If you want peers to pressure-test your raise, the Founder Connects Residency is virtual and matches founders into Squads of 8 to 10 at a similar stage. Founder Connects Meetups in Dubai and MENA, plus Nairobi, bring founders, operators and investors into the same room.
Angel Return Expectations FAQ
What return do angel investors in MENA expect?
On the deals that work, angels backing pre-seed and seed rounds in the UAE and MENA usually look for 10x to 30x their cheque. They expect many cheques to return little, so the winners have to cover the losses across the portfolio.
How much equity do angels take at pre-seed in the UAE?
Angels often target 7% to 15% combined ownership at pre-seed or seed, with individual cheques commonly between AED 35,000 and AED 185,000, according to our guide to angel investors in Dubai. The exact stake depends on the valuation, the instrument and the size of the round.
What exit value makes an angel cheque worth it?
Divide the target payout by the angel's stake. A $250,000 cheque at a $4 million post-money valuation buys 6.25%, so a 10x return needs an exit of about $40 million and 30x needs about $120 million, before later rounds dilute the stake.
How long do angels expect to wait for an exit?
Plan for 5 to 10 years in the UAE and MENA. Our guides to angel holding periods and exit expectations over 5 to 10 years cover the timeline in detail.
Should I raise on a SAFE or a priced round?
A SAFE is faster and defers the valuation to the next priced round, while a priced round fixes ownership today. Either way, model the conversion so you know the stake each angel will end up with. Our comparison of convertible notes vs SAFE for UAE startups walks through the mechanics.

Building in MENA? You don't have to do it alone.
Join 300+ founders in the Founder Connects Residency. Monthly squad calls, warm intros, $3M+ in perks, and much more. All for less than your monthly coffee budget.
Popular posts



Founder Connects is a premium MENA tech founder community. Meetups in Dubai and across MENA, Residency Squads of 8–10, and 400+ vetted WhatsApp founders (apply and screened).